
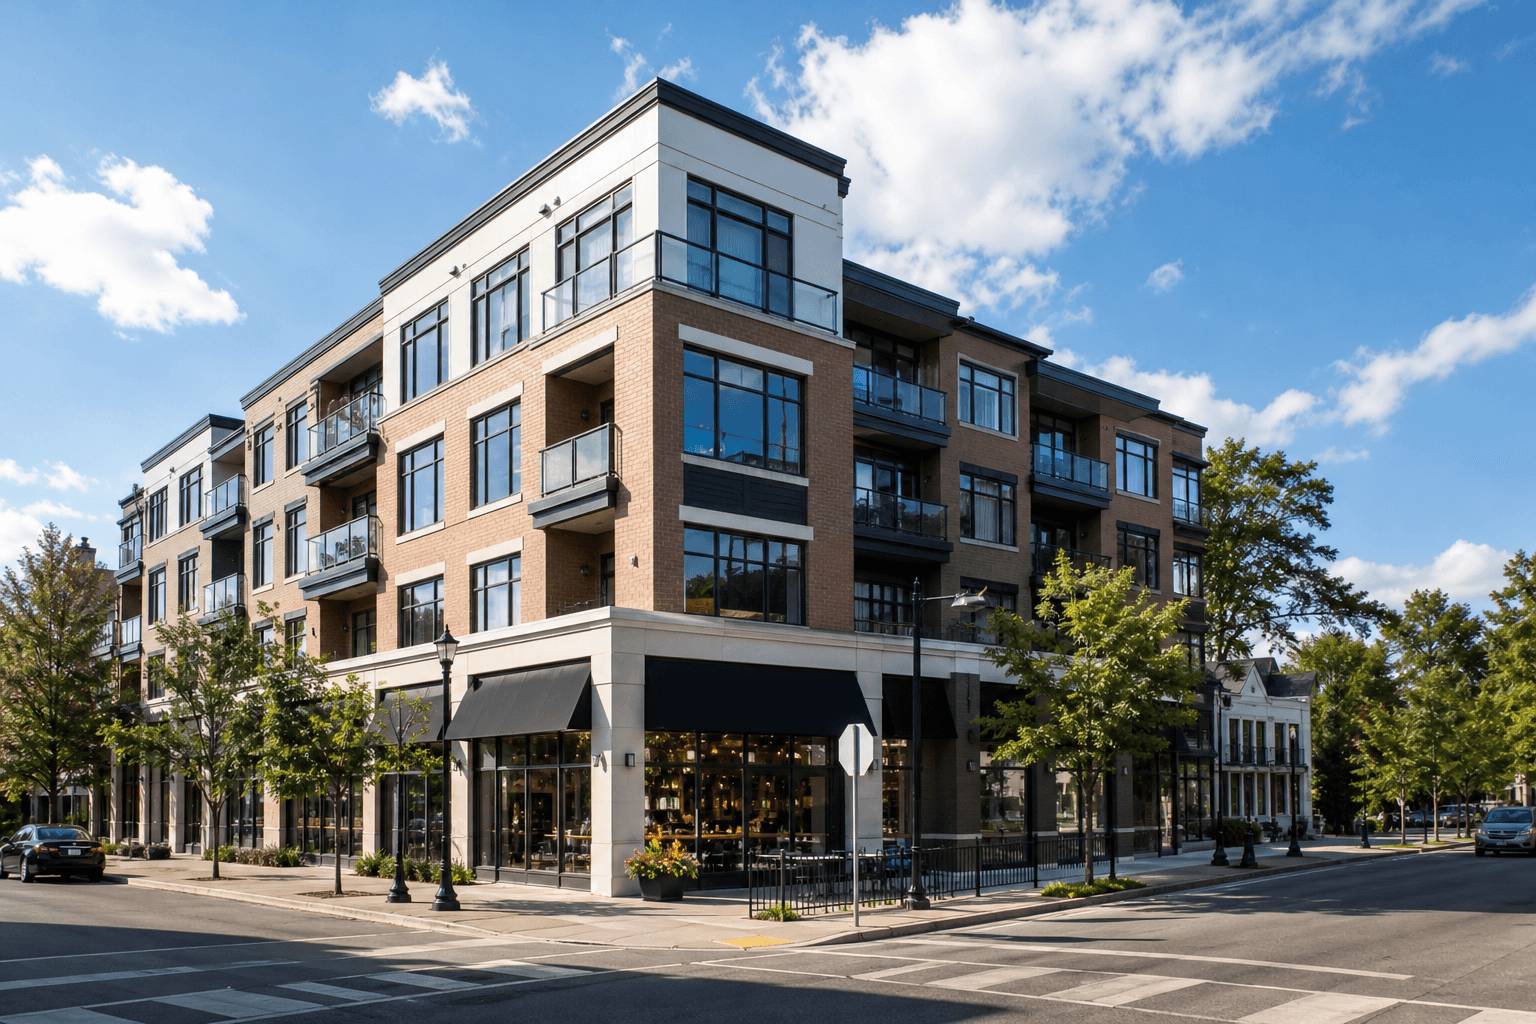
A mixed-use property combines residential and commercial space, such as apartments above retail, a storefront with a residence, or business premises with an attached home. The right mortgage route depends on the property's actual use and financial structure, not simply the label “mixed-use.”
Depending on the residential-commercial mix, occupancy, income, zoning, leases, valuation, borrower profile, and financing purpose, a lender may assess the property through a residential, commercial, alternative, or private financing approach. No single category applies to every property.
Quick summary

- A mixed-use property contains residential and commercial space, but no universal percentage determines its mortgage category.
- Classification can vary between institutions. Use, zoning, leases, income, valuation, and borrower finances all matter.
- Residential financing may suit a predominantly residential property, while commercial or specialized financing may better fit substantial business activity or complex income.
- Purchases, refinances, and renewals can involve different assessments.
- Prepare property details, leases, income records, existing mortgage information, and valuation documents before applying.
What is a mixed-use property?
In plain buyer language, a mixed-use property has residential and commercial functions in the same building or property. Examples include retail on the ground floor with apartments above, offices beside residential suites, or a residence attached to a business.
The Canada Mortgage and Housing Corporation uses “mixed-use development” in its housing glossary. However, the description alone does not determine how a lender will structure or underwrite the mortgage. The practical questions are how the property is used, occupied, valued, and expected to generate income.
An owner-occupied shop with a home above it may raise different questions from a building with several residential units and a leased restaurant. A property purchased for an operating business may also be assessed differently from one bought primarily as a rental investment.
What lenders may assess

Requirements vary, but the following details help a lender understand both the real estate and the borrower.
Property use and occupancy
Explain what each area is used for, who occupies it, and whether the residential and commercial portions are physically separated. Identify any owner-occupied space, residential tenants, commercial tenants, or owner-operated business.
Residential-commercial mix
The relative importance of each use can influence the assessment, but do not assume a particular percentage guarantees residential or commercial treatment. Layout, income, use, and lender policy may matter together.
Zoning and permitted use
Confirm how the property is legally permitted to be used and whether the current use matches municipal approvals. Zoning, licenses, occupancy arrangements, and planned changes may affect the review.
Income and leases
Rental income, commercial rent, business revenue, and existing leases may form part of the analysis. Clarify which income comes from tenants, which comes from your business, and whether leases are new, informal, expiring, or subject to special terms.
Valuation and condition
A mixed-use building may require valuation that reflects both its residential and commercial components. Condition, location, layout, income potential, comparable properties, and the distinction between real estate and business assets may all be relevant.
Borrower profile and purpose
Income, credit history, assets, liabilities, business structure, and experience may be reviewed alongside the property. The purpose also matters: purchasing, taking equity out, consolidating debt, funding improvements, or renewing an existing mortgage can create different questions.
CMHC mortgage data standards acknowledge that institutions may classify rental, multi-unit, and mixed-use properties differently for reporting purposes. This is not a binding lending rule, but it is a useful reminder not to assume every institution will assess the same property identically.
Compare potential mixed-use mortgage routes
This comparison is a starting point, not a promise that a particular route will be available.
| Potential route | When it may warrant investigation | Key tradeoffs |
|---|---|---|
| Residential mortgage | Residential use is dominant and the property fits residential lending criteria. | The process may be familiar, but commercial activity, income, and permitted use still need review. |
| Commercial mortgage | The property has meaningful commercial use, substantial business activity, or complex income. | Assessment may focus on leases, income, operations, and valuation. Costs and terms may differ from residential financing. |
| Alternative financing | The borrower or property does not fit a conventional assessment cleanly. | Flexibility may involve different pricing, fees, conditions, or repayment considerations. |
| Private mortgage | A short-term or specialized solution is being considered. | Review interest, fees, term, renewal risk, repayment plan, and exit strategy carefully. |
Residential and commercial mortgages can differ in how property, income, risk, and repayment are evaluated. Before comparing offers, review commercial mortgage financing in the context of your property.
A practical decision tree
- Is the property primarily residential? Ask whether a residential assessment is possible while fully disclosing the commercial activity.
- Is commercial use meaningful? Investigate commercial financing alongside any residential option if business operations or commercial leases are central.
- Is it income-producing with multiple units? Organize the rent roll, leases, vacancies, and operating expenses, then ask how residential and commercial income will be considered together.
- Is the structure unusual? If zoning, ownership, construction, occupancy, income, or valuation is complex, ask whether alternative or private options need consideration and what the exit plan would be.
At every stage, ask which route reflects the property's use and borrowing purpose while keeping total cost and future flexibility manageable.
Purchase, refinance, or renewal
Buying a mixed-use property
For a purchase, the review begins with proposed use, price, down payment, financing structure, and expected income. Obtain information about leases, occupancy, zoning, condition, and the separation between residential and commercial areas before making an offer.
Refinancing
A refinance may replace an existing mortgage, access equity, consolidate debt, fund improvements, or change the financing structure. Explain where the funds will go because the purpose can affect documentation and route suitability.
Renewing an existing mortgage
A renewal is not always a matter of accepting the current lender's offer. If use, leases, income, ownership, value, or borrowing needs have changed, the mortgage may require fresh assessment. Compare the offer with other suitable mortgage renewal options before signing.
For every purpose, compare more than the interest rate. Consider term, fees, penalties, flexibility, documentation, repayment, and what happens when the next term ends.
Mixed-use mortgage preparation checklist
Requirements are lender-dependent, so use this as a discussion checklist.
- Borrower details: identification, income, self-employment or business ownership, assets, liabilities, credit information, and ownership structure.
- Property details: address, purchase agreement or ownership details, description of all residential and commercial areas, occupancy, vacancies, zoning, permitted use, renovations, and condition.
- Leases and income: current leases, amendments, rent schedules, deposits, expiry dates, arrears, rental records, business records, and operating costs.
- Mortgage details: current statement, balance, maturity or renewal date, payment details, and prepayment terms.
- Valuation information: appraisals, inspections, environmental or construction reports, renovation information, requested financing, available equity, and transaction costs.
When choosing professional help, ask how residential and commercial possibilities will be compared, how rental and business income will be reviewed, what costs may arise, and whether the route suits a purchase, refinance, or renewal. This guide to choosing a commercial mortgage broker can help you prepare.
Frequently asked questions
Does every mixed-use property require a commercial mortgage?
No. Residential, commercial, alternative, or private financing may each warrant investigation depending on use, income, zoning, valuation, and borrower circumstances.
Can I refinance or renew a mixed-use mortgage?
Potentially. A refinance may require review of the use of funds, while a renewal may prompt reassessment if the property, income, leases, ownership, or lender requirements have changed.
What documents should I prepare?
Start with borrower income and asset details, property use and occupancy, zoning, leases, rental and business income, operating costs, existing mortgage details, and valuation documents. The final list depends on the lender.
Are apartments above retail treated differently from a residence attached to a business?
They may be. Apartments above retail can involve multiple residential units and commercial leases, while an attached residence may raise different questions about owner occupancy, business income, and separation of personal and commercial use.
Conclusion: Start with the property and its use
Do not choose a mortgage category from the “mixed-use” label alone. Document how the property is used, who occupies it, how income is generated, what the leases and permitted uses are, and whether you are buying, refinancing, or renewing.
Then compare suitable routes by total cost, flexibility, documentation requirements, and future repayment implications. Classification can vary between institutions, so a property-specific review is more useful than relying on an assumed threshold or headline rate.
For mixed-use property financing and other Southern Ontario mortgage needs, speak with Amarpreet Bhui, a Mississauga-based mortgage professional offering commercial and investment property mortgage support.
Last updated October 21, 2026