
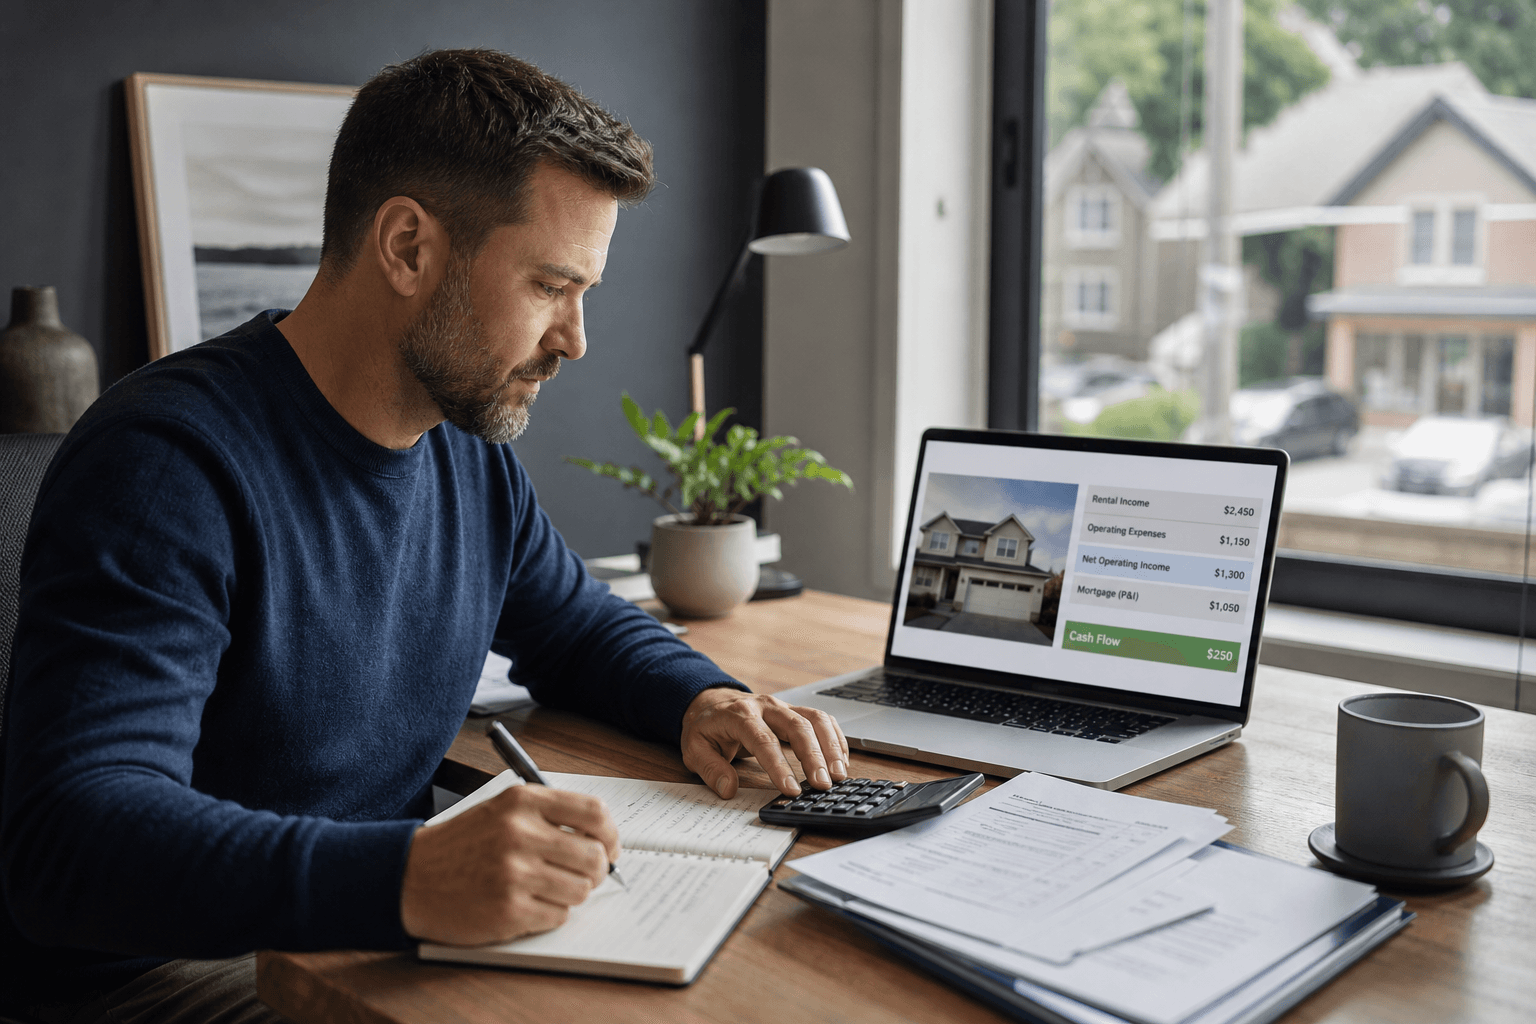
DSCR Mortgage Basics: What Investors Should Understand
DSCR, or debt service coverage ratio, compares income generated by an investment property with the debt payments associated with it. In mortgage discussions, it can help indicate whether a rental property appears capable of supporting its financing. It is not, however, a universal approval formula or a guarantee of mortgage approval.
For investors in Mississauga and across Southern Ontario, understanding DSCR can make rental property financing conversations more productive. The key is to know what the measure is intended to show, which figures may affect it, and why lenders still assess the property and borrower as a whole.
Quick summary

- DSCR focuses on the relationship between property-related income and debt-service obligations.
- It does not automatically replace review of credit, income, existing debts, assets, or documentation.
- Rent, vacancies, operating expenses, taxes, insurance, maintenance, and debt payments may affect the calculation.
- Lender policies differ, so a DSCR result is a starting point rather than a guaranteed threshold.
- Investors should prepare both property figures and personal financial information before seeking financing.
What does DSCR mean in mortgage discussions?
Debt service coverage ratio describes a property’s ability to cover debt-service obligations from its income. In straightforward terms, the discussion asks whether the cash flow associated with a rental property appears sufficient to support the mortgage payments and other obligations included in the lender’s assessment.
The exact calculation can vary. Lenders may define property income, operating expenses, and debt service differently. Treatment of projected rent or other costs may also depend on the property and application. There is therefore no single DSCR number that universally determines whether an Ontario investor qualifies.
DSCR is best understood as one lens in an investment-property mortgage discussion. It can show whether a property’s financial assumptions deserve further review, but it does not describe the complete risk of an application.
Property cash flow is not the same as personal income

A DSCR-focused conversation emphasizes the property’s operating performance. That differs from reviewing the borrower’s employment or self-employed income, credit history, existing obligations, assets, and wider financial position.
Investors should not assume that a property-level measure makes personal qualification irrelevant. A lender may still need to understand who is borrowing, how the application will be documented, what other debts exist, and whether the proposed financing fits the borrower’s circumstances.
A rental property can appear promising while the full application raises separate questions. Conversely, conservative property cash-flow assumptions may still warrant discussion as part of a broader financing strategy.
A simple hypothetical example
Consider this purely illustrative example. Suppose a rental property produces $2,500 per month in income after the expenses included in the example, while the debt-service amount being examined is $2,000 per month. Dividing $2,500 by $2,000 produces 1.25.
This is only a teaching example. It is not a recommended minimum, a Canadian lending standard, or an indication that a lender would use those exact figures. If rent falls, expenses rise, or additional obligations are included, the result can change.
The practical lesson is that the quality and treatment of the underlying numbers matter more than memorizing one ratio. Ask which income, costs, and debt payments are being used.
Why DSCR matters for investment-property financing
For a rental purchase or refinance, property cash flow is central to the investment decision. A DSCR discussion can help an investor test whether proposed financing appears consistent with expected income and expenses before moving further into an application.
This may be useful when comparing a potential rental with an existing investment, reviewing a refinance, or considering another property. It encourages attention to the property’s numbers rather than only its purchase price or anticipated appreciation.
DSCR is not a substitute for an investment-property mortgage assessment. Review investment property mortgages, then discuss how the property, borrower, and intended use may be assessed.
Information to prepare before discussing DSCR financing
Organize information that explains both the property and your wider financial position. These are discussion topics, not universal lender requirements.
- Expected rental income: Note the proposed rent, its source, and whether the property is already tenanted.
- Operating expenses: Gather available details for taxes, insurance, utilities, maintenance, management, and other recurring costs.
- Debt service: Identify the proposed mortgage payment and other relevant property financing.
- Transaction details: Explain the purchase price, requested financing, existing mortgage, or reason for refinancing.
- Equity or down payment: Clarify available funds or equity and the proposed structure.
- Borrower information: Prepare details about income, credit, existing debts, assets, and other obligations.
- Property use: Explain whether the property will be a long-term rental or another permitted use.
Why the quality of the numbers matters
Projected rent is not the same as verified rental income. A new purchase may rely on market estimates, while an existing rental may have leases, payment history, and operating records that provide more context. Lenders may assess these situations differently.
Vacancy and maintenance assumptions also deserve attention. Optimistic rent and minimal expenses can make a property appear stronger than it performs. Test whether projected income remains reasonable if a unit is vacant, repairs are needed, or costs increase.
Ask which expenses are included, which income sources are accepted, and how projections are reviewed. The answers may vary by lender, property type, documentation, and application details.
Why DSCR criteria differ between lenders
DSCR is not a standardized mortgage product with identical Canadian rules. Lenders can differ in their treatment of rental income, operating expenses, property types, documentation, credit information, existing debts, and overall risk.
One lender may view projected rent or a particular property type differently from another. Policies may also differ around refinance proceeds, the number of properties an investor owns, and supporting documentation.
Compare the calculation method with the lender’s broader requirements and the specific facts of the proposed transaction rather than judging financing from a ratio alone.
Tradeoffs and limitations investors should understand
A property-level measure keeps attention on the asset’s income and debt obligations. It may help determine whether a purchase or refinance deserves further review.
Its limitation is that it may not capture every borrower obligation or risk. Personal debts, credit history, documentation, assets, property condition, and intended use can still matter.
A calculation based on projections also differs from one based on current records. A strong projected result does not remove the need to validate assumptions, and a weaker result does not explain every financing option. The appropriate response is a broader review.
When should an investor seek a DSCR-focused discussion?
Consider a DSCR-focused conversation when evaluating a rental purchase, refinancing an investment property, or considering another property. It can help identify which assumptions need better documentation before making an offer or submitting an application.
Start with an affordability review if you are still determining your budget or comparing properties. An affordability tool supports early planning but is not mortgage approval. Review what to check before using an affordability calculator.
Seek a fuller investment-property financing discussion when you have a specific property, refinance objective, or portfolio plan. That conversation can address property figures alongside your personal financial context.
Questions to ask before pursuing this type of financing
- How will rental income be calculated?
- Which expenses, taxes, insurance, maintenance costs, and vacancy assumptions will be considered?
- Which debt payments are included?
- What documentation supports current or projected rent?
- Is the property type and intended use eligible?
- How will credit, income, existing debts, and other obligations affect the application?
- Would a purchase, refinance, or alternative structure better fit the objective?
- Which assumptions should be stress-tested?
Frequently asked questions about DSCR mortgage basics
What does DSCR measure?
DSCR measures the relationship between investment-property income and the debt-service obligations considered in an assessment. The items included vary by lender and application.
Does DSCR replace personal mortgage qualification?
No. It does not replace review of credit, income, documentation, existing obligations, assets, and complete financial circumstances.
Which expenses can affect a DSCR discussion?
Potential discussion points include rent, vacancy, taxes, insurance, maintenance, management costs, utilities, and debt payments. Treatment depends on the lender and file.
Does a DSCR result guarantee mortgage approval?
No. Property details, borrower circumstances, documentation, credit, income, lender criteria, and overall risk assessment can all affect the decision.
Use DSCR as a starting point, not a promise
DSCR mortgage basics come down to understanding how a rental property’s income may compare with its related debt obligations. That perspective can help investors organize figures, test assumptions, and ask focused questions about investment-property financing.
There is no universal ratio, calculation method, or approval rule for every lender or Southern Ontario property. Prepare property figures, personal financial information, and intended use, then seek a review of the complete application.
MiiGrowth is a Mississauga-based mortgage brand serving Southern Ontario and offers investment-property financing support. To discuss your circumstances, visit MiiGrowth.
Last updated September 17, 2026